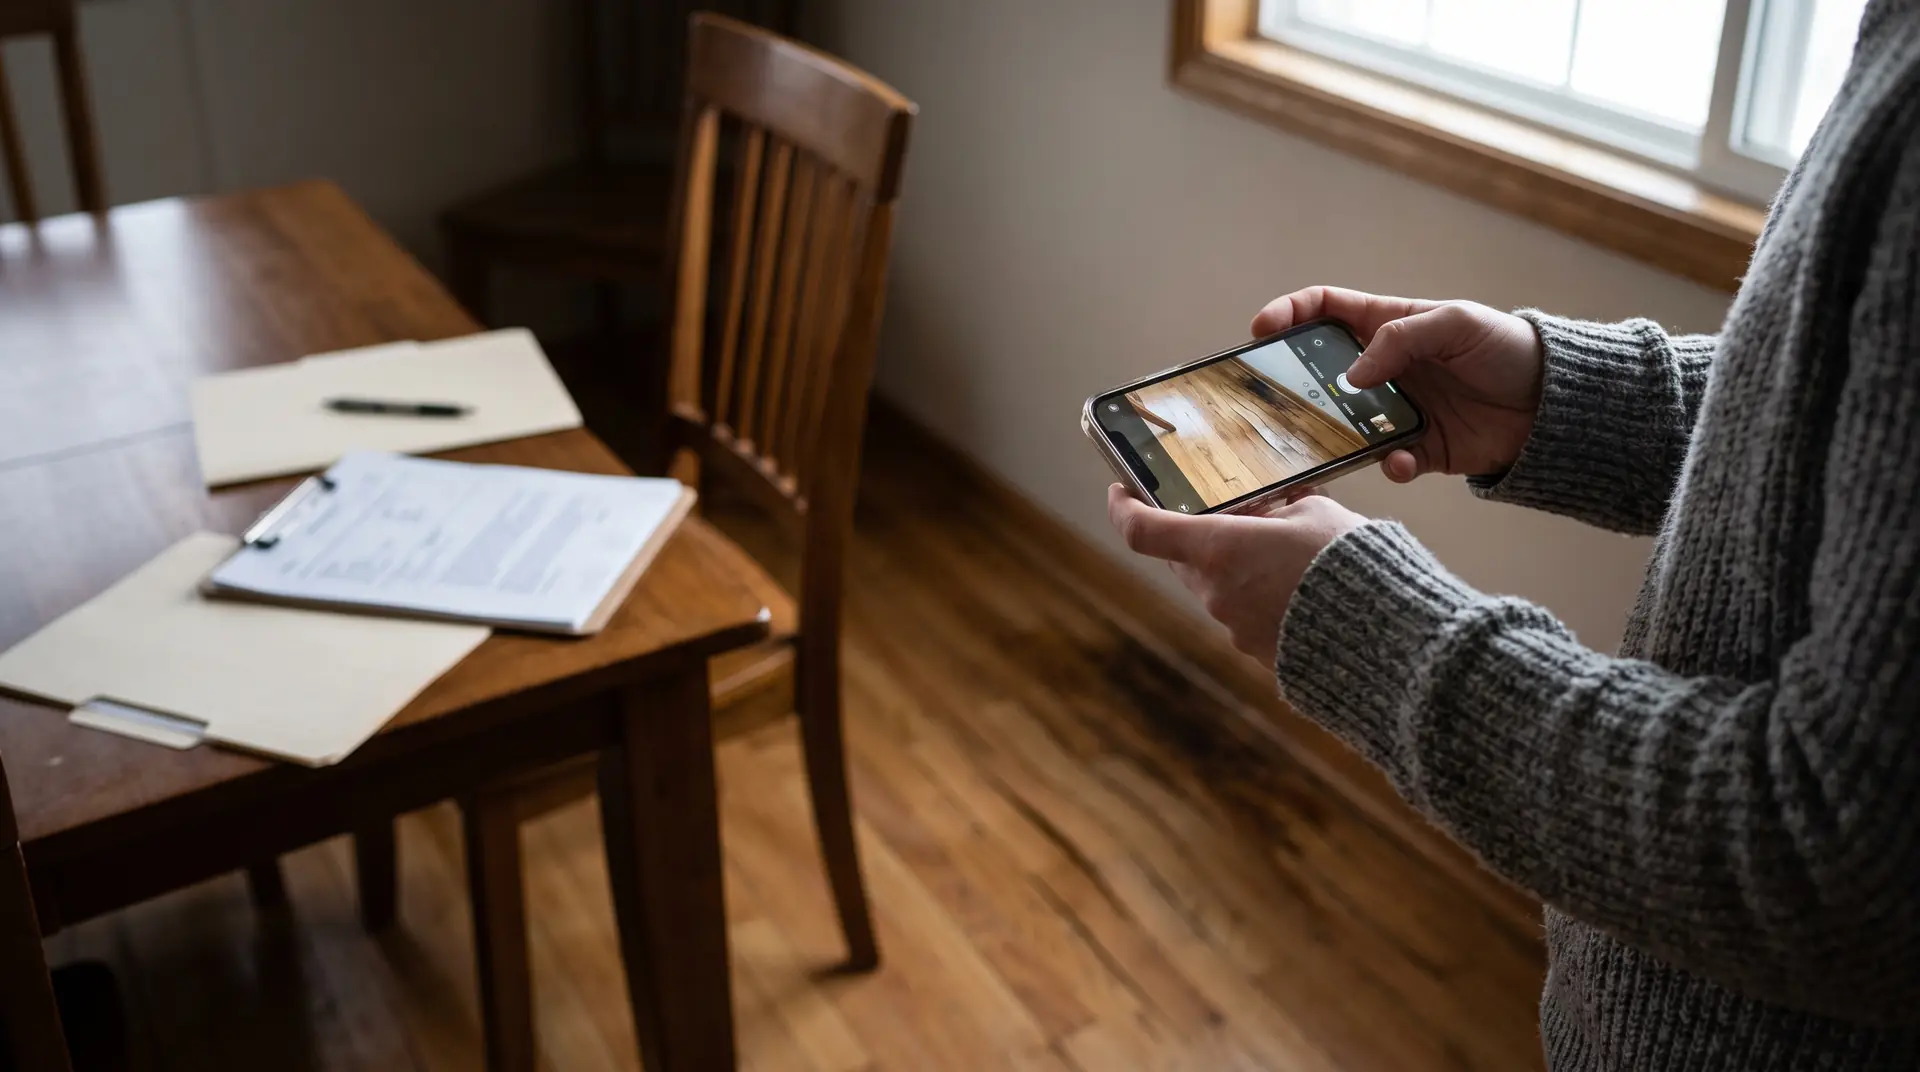
Homeowner photographing a warped wet floor for an insurance claim
Calls answered 24/7

Water Damage Insurance Claim Help for Hackensack and Bergen County Homeowners

Water damage and an insurance claim at the same time is a lot. The claim goes smoother when you know which policy applies, what to photograph and who does what.

This page is general information, not legal or insurance advice. Your policy wording decides what's covered.

Number for Water Damage, Fire, Mold & Sewage

Undercroft Restoration is a free referral service, not a restoration company. Calls are connected to independent local service providers that serve your area, and calls may be recorded. The work is done by those providers, not by this site.

  • One Call Connects You
  • No Obligation to Hire
  • Calls Answered 24/7
  • Document First
10 working daysFor NJ insurers to start investigating
30 daysTo settle after proof of loss
FloodExcluded from standard homeowners policies
30 daysUsual NFIP flood policy waiting period
01

Which Policy Pays: Burst Pipes, Floods, Sewer Backups and Mold in New Jersey

The first question an adjuster asks is where the water came from. The answer decides which policy, if any, applies.

What happened Usually handled by Notes
Pipe, water heater or appliance failed suddenly Homeowners, condo (HO-6) or renters policy Slow leaks and wear are usually excluded
River, brook, storm or surface water came in Flood policy (NFIP or private) Standard homeowners policies exclude flood
Sewage or water backed up through a drain or sump Water backup endorsement, if you have one Often a separate, smaller limit
Fire, smoke or the water used to fight a fire Homeowners, condo (HO-6) or renters policy Fire is a standard covered risk; hose water is part of the fire loss; ask about additional living expenses
Mold Usually only after a covered water loss Often capped; long-term moisture usually excluded
01

Burst Pipe Insurance Claim: Usually Homeowners, If It Was Sudden

A pipe that splits, a washer hose that bursts, a water heater that lets go overnight: most homeowners, condo and renters policies cover sudden and accidental discharge. What they usually don't cover is the damage from a slow drip that went on for weeks, or the cost of the failed part itself. Report it quickly; a delay can raise questions about how long the leak ran. More on these losses on the water damage restoration page.

02

Basement Flood Insurance Claim: Flood Policy or Backup Endorsement?

A flooded basement can fall under three different answers. If a river, brook or surface water came in, it's a flood claim, and only a flood policy covers it. FEMA's basement fact sheet explains that NFIP flood insurance covers certain building items below grade, like furnaces, water heaters, electrical boxes, sump pumps and cleanup, but not finished floors, walls or most contents. If the sump pump failed or water backed up through a drain, that's usually a water backup endorsement on your homeowners policy. If groundwater seeped in slowly, it may not be covered by either. See flooded basement cleanup.

03

Sewer Backup Insurance Coverage Is Usually an Add-On

As The Hanover explains, homeowners insurance doesn't typically cover water backup damage; it's optional coverage you add on. Check your declarations page for "water backup" or "sewer and drain backup," and note its limit. See sewage cleanup.

02

Help Filing Water Damage Claim Paperwork: What to Photograph and Keep

New Jersey's Department of Banking and Insurance tells policyholders to photograph all damage before throwing anything away. That one habit makes more difference to a claim than anything else. Keep:

  • Photos and video of every affected room, wide and close up, including the waterline on walls and the source of the water.
  • A list of damaged items, with brand, model, age and where you bought them if you know.
  • Samples of carpet and pad, and of any unusual material, before they're hauled away.
  • Receipts for anything you paid for to stop the damage: fans, a hotel night, a plumber, emergency extraction.
  • The plumber's invoice or report naming the cause, like "failed supply line" or "split pipe in exterior wall."
  • The restoration company's documents: daily moisture readings, photos and the written scope.
  • A log of every call and email with your insurer: date, name and what was said.

Tell your insurer promptly, and take reasonable steps to stop more damage. Waiting for the adjuster while water sits and mold grows can hurt the claim.

03

Water Damage Claim Documentation From the Restoration Side: Moisture Logs, Photos and Scope

A good restoration company produces paperwork your adjuster can work from:

  • Before photos of every wet area and the source.
  • A moisture map showing where the water went, including inside walls and under floors.
  • Daily readings of temperature, humidity and material moisture, which the IICRC's drying standard calls for, until materials reach the dry standard.
  • A written, itemized scope: what was removed, what equipment ran and for how long, and what the rebuild involves.
  • After photos once the area is dry and before walls close.

A good crew photographs and measures on day one and sends final photos when the job wraps up. Ask the company you're connected with for copies of everything.

04

New Jersey Claim Timelines Insurers Must Follow

New Jersey's claim settlement rules, N.J.A.C. 11:2-17.7, set deadlines for insurers:

  • Investigation: an insurer must begin investigating within 10 working days of being notified of the claim.
  • Settlement: for property claims like water damage, within 30 calendar days of receiving a properly completed proof of loss.
  • Delays: if it can't settle in time, it must send you written notice explaining why, then an updated notice within 45 days and every 45 days after that.
  • Payment: once you've agreed on an amount, it must be paid within 10 working days.

If you think your insurer isn't following these rules, you can contact the NJ Department of Banking and Insurance.

05

Adjusters, Public Adjusters and Restoration Crews: Who Does What

  • The company adjuster works for your insurance company. They inspect the damage, review your documents and recommend what the policy pays.
  • A public adjuster works for you. Public adjusters are licensed by New Jersey's Department of Banking and Insurance, and they can negotiate the claim on your behalf. They charge a fee, usually a share of the settlement, so ask about it up front.
  • The restoration crew removes the water, dries the structure and documents what they found and did. They don't negotiate your claim, and you should be wary of any contractor that says it will "handle" it.

When you talk to your insurer's adjuster, stick to the facts you know: when you found the water, where it came from if you know, what you did about it. Don't guess about the cause or how long it's been leaking. Show them your photos and documents, and ask for anything they tell you in writing.

06

Water Damage Claim Assistance This Line Can and Can't Offer

Here's the straight version. Undercroft Restoration is a referral service. When you call (201) 409-9820, you're connected with an independent, third-party restoration company that serves your area. That company does the work and produces the documentation. Some companies bill insurers directly; some don't. That depends on the company, so ask them.

Undercroft Restoration doesn't handle claims, talk to your insurer for you, or promise anything about coverage. What this line can do is get you connected quickly, and this page gives you the information to file a clean claim yourself. For how the line works across every service, see the home page.

Looking for a Restoration Company That Works With Insurance? Ask These Questions First

  • Do you bill my insurer directly, or do I pay you and get reimbursed?
  • What happens if my claim is denied or only partly paid?
  • Will I get a written scope before work starts, and written change orders if it grows?
  • Will you give me copies of all photos and moisture readings?
07
Call any time

Need Help Now? Call and Get Connected With a Bergen County Restoration Company

Calls answered 24/7, from Bergen and Middlesex counties. Take photos first if it's safe, then call.

Undercroft Restoration is a free referral service, not a restoration company. Calls are connected to independent local service providers that serve your area, and calls may be recorded. The work is done by those providers, not by this site.

Pick the number for your problemServing Bergen and Middlesex Counties, NJ ยท Calls answered 24/7
Questions

What New Jersey Homeowners Ask About Water Damage Claims

Still have a question?

Calls answered 24/7. Pick the number for your problem, then say your town and what happened.

Should I call my insurer or a restoration company first?

Stop the water and make the area safe, take photos, then do both. Getting the water out quickly is a reasonable step to prevent more damage, which your policy expects. Notify your insurer right away if you can.

Can I start cleanup before the adjuster visits?

Yes, after you've photographed everything. Extraction and drying to stop further damage shouldn't wait. Keep damaged items or samples until the adjuster says they can go, and keep every receipt.

Does homeowners insurance cover a flooded basement?

It depends on where the water came from. A burst pipe is usually covered. River or surface flooding needs a flood policy. A sump failure or backup usually needs a backup endorsement. Slow groundwater seepage often isn't covered.

What not to say to an insurance adjuster about water damage?

Don't guess. Don't say how long it's been leaking unless you know, and don't agree to a cause you're not sure of. Stick to what you saw and did, and back it up with photos and documents.

Is mold covered?

A mold insurance claim is usually covered only when the mold came from a covered, sudden water loss, and many policies cap mold coverage. Mold from long-term humidity or slow leaks is usually excluded.

What if my claim is denied?

Ask for the reasons in writing, with the policy language they rely on. Review it against your policy. You can contact the NJ Department of Banking and Insurance, hire a licensed public adjuster, or talk to an attorney.

Do renters have coverage for their belongings?

Only through their own renters policy. The landlord's policy usually covers the building, not the tenant's things. Renters policies may also cover a place to stay while the unit is repaired.

How long does an NJ insurer have to pay?

Under N.J.A.C. 11:2-17.7, property claims should be settled within 30 calendar days of a properly completed proof of loss, with written notice if more time is needed. Agreed amounts must be paid within 10 working days.

Call (201) 409-9820Water, Fire, Mold & Sewage